|
The Week Ahead: Highlights
Asia-Pacific Preview
China Monthly Reports in Focus
By Brian Jackson, Econoday Economist
Chinas monthly activity data for October will be the main
focus in the Asia-Pacific region in the week ahead. Last months data showed
stronger retail sales, steady growth in industrial production and another big
drop in investment spending. Officials again noted the impact of a complex and
volatile external environment. Official PMI survey data for October published
late last month showed renewed contraction in both the manufacturing and
services sectors, suggesting that the data in the week ahead may show subdued
conditions. The data will also be accompanied by an updated assessment of
conditions and policy settings and followed by the Peoples Bank of China
monthly review of loan prime rates.
Australia will publish monthly employment and quarterly
wages data. Earlier this month, officials at the Reserve Bank of Australia
raised policy rates for the fifth time this year and noted that this policy
tightened had tightened financial conditions and contributed to a higher
unemployment rate. They expect the unemployment rate to rise further but also
stressed that their priority is to return inflation to their target range of
two percent to three percent. This suggests that subdued labour market data
next week will not come as a surprise and will not be enough to dissuade
further policy tightening from being considered in upcoming meetings. The
minutes of this months policy meeting will also be published in the week
ahead.
Singapore trade data will likely show another month of very
strong growth in exports and imports. Taiwan, South Korea and China have
already reported strong trade flows in October and Singapores PMI survey
showed that new export orders grew at a faster pace in October. New
Zealand will publish trade data and producer price data, while India will
publish wholesale price data. Thailand GDP data and Hong Kong CPI data are also
scheduled for release.
US Preview
Markets to Eye October FOMC Meeting Minutes for Rate Hike
Outlook
By Theresa Sheehan, Econoday Economist
The information set for release in the November 16 week
includes the minutes of the October 27-28 FOMC meeting. The content of the
minutes will reflect conditions three weeks earlier. It will be interesting to
determine just how much support a rate hike had at that time among the 19
committee participants, not just the 12 voters which includes two dissents
against the decision to leave the fed funds target rate range at 3.75 to 4.00
percent. Given the tone of the October data for the consumer price index and
final-demand producer price index, and comments from various Fed policymakers,
the likelihood of a rate hike at the December 8-9 meeting seems high.
There are a number of reports for November on the calendar
in the coming week that will reflect economic conditions around the midpoint of
the fourth quarter 2026.
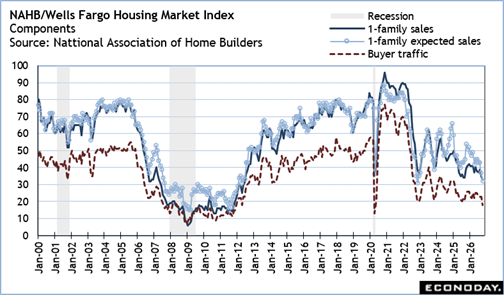
The NAHB/Wells Fargo housing market index for November at
10:00 ET on Tuesday probably wont show any significant improvement from slump
to 29 in October when it was the lowest since 29 in July 2012 when the housing
market was only just recovering from its crash in 2008. The main culprit has
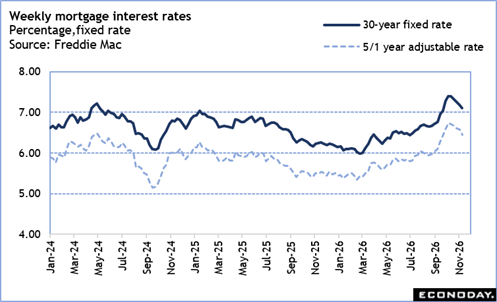
been the quick rise in mortgage rates in September and October. The Freddie Mac
average weekly rate peaked at 7.40 percent for a fixed rate mortgage in the
weeks of October 8 and 15 and has since declined to 7.11 percent in the
November 12 week. This may be enough to lift some buyer activity, but not
enough to tap into pent up demand quite yet.
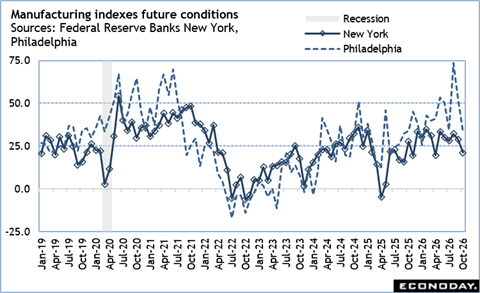
The manufacturing surveys from the New York and Philadelphia
Feds will be released at 8:30 ET on Monday and Thursday. These are the two
earliest takes on conditions in the factory sector in the month of November.
The general business conditions indexes for the neighboring regions do not move
in tandem. The New York measure tends to fluctuate between firmer and softer
readings each month. If this pattern is followed, the 25.5 reading in October
will be followed by much slower expansion in November. The Philadelphia index
has been trending down in the past two months to a much more modest pace of
expansion. It will probably level off in November near 20.9 in the prior month
with order backlogs to maintain the pace even though new orders declined in
October.
The Week Ahead: Econoday Consensus Forecasts
Monday
Japan GDP for Third Quarter (Mon 0850 JST; Sun 2350
GMT; Sun 1850 EST)
Consensus Forecast, Q/Q: 0.1%
Consensus Range, Q/Q: -0.1% to 0.4%
Consensus Forecast, Y/Y: 1.2%
Consensus Range, Y/Y: 1.1% to 1.5%
Japans economy is expected to grow for a fourth straight
quarter in the July-September period, but at only a modest pace close to zero.
Continued demand related to artificial intelligence development is expected to
support capital investment and help underpin overall economic growth.
Still, private consumption, which accounts for more than
half of Japans gross domestic product (GDP), is expected to decline for the
first time in 10 quarters as rising inflation, driven in part by higher food
prices and other goods, has heightened consumer cost-consciousness and curbed
spending.
A series of rainstorms, lower-than-usual temperatures in
some regions and natural disasters, including strong earthquakes that hit
Kumamoto on the southern main island of Kyushu and heavy rain in Chiba
Prefecture near Tokyo, may also have affected production and consumption during
the third quarter, weighing on GDP.
The economy is expected to maintain slight growth, supported
by continued increases in capital investment amid sustained demand related to
AI projects, including the construction of data centers and factories producing
equipment and components used in the AI sector. Domestic demand is also
expected to provide some support to the economy.
Against this backdrop, Japans preliminary real GDP is
forecast to rise a modest 0.1% on the quarter in the July-September period, or
an annualized 0.3%. This would mark a fourth straight quarter of growth,
although the pace would slow from a 0.4% quarterly rise, or an annualized 1.4%
increase, in the second quarter.
Private consumption, which accounts for about 55% of total
domestic output, is forecast to fall 0.2% on the quarter, marking its first
decline in 10 quarters after remaining flat in the April-June quarter.
China Fixed Asset Investment for October (Mon 1000
CST; Mon 0200 GMT; Sun 2100 EST)
Consensus Forecast, Year to Date on Y/Y Basis: -7.0%
Consensus Range, Year to Date on Y/Y Basis: -7.1% to -7.0%
The dramatic declines in fixed asset investment expected to
continue with a 7.0 percent decrease in October after a 7.2 percent drop in
September.
China Industrial Production for October (Mon 1000
CST; Mon 0200 GMT; Sun 2100 EST)
Consensus Forecast, Y/Y: 5.3%
Consensus Range, Y/Y: 5.3% to 5.5%
Industrial output growth expected slightly lower at 5.3
percent in October from 5.5 percent in September.
China Retail Sales for October (Mon 1000 CST; Mon 0200
GMT; Sun 2100 EST)
Consensus Forecast, Y/Y: 0.8%
Consensus Range, Y/Y: 0.6% to 1.7%
Consumption shows no sign of recovering to normal growth
rates. The consensus sees retail sales barely higher at 0.8 percent on year in
October after rising 1.1 percent in September.
Eurozone Industrial Production for September (Mon 1100
CET; Mon 1000 GMT; Mon 0500 EST)
Consensus Forecast, M/M: 0.4%
Consensus Range, M/M: 0.3% to 0.9%
Consensus Forecast, Y/Y: 0.3%
Consensus Range, Y/Y: -0.6% to 1.0%
Industrial output expected to rebound by 0.4 percent on
month and 0.3 percent on year in September after declines of 0.5 percent on
month and 1.1 percent on year in August.
Canada CPI for October (Mon 0830 EST; Mon 1330 GMT)
Consensus Forecast, CPI - M/M: 0.3%
Consensus Range, CPI - M/M: 0.1% to 0.4%
Consensus Forecast, CPI - Y/Y: 3.2%
Consensus Range, CPI - Y/Y: 3.0% to 3.3%
Forecasters look for hotter inflation at 0.3 percent on
month and 3.2 percent on year in October after gains of 0.1 percent and 3.1
percent, respectively, in September. High energy costs are to blame for raising
inflation just ahead of the next Bank of Canada meeting.
US Empire State Manufacturing Index for November (Mon
0830 EST; Mon 1330 GMT)
Consensus Forecast, Index: 17.0
Consensus Range, Index: 10.0 to 30.0
Slower but decent growth is the call with the index expected
at 17.0 in November versus 25.5 in October.
Tuesday
UK Labour Market Report for November (Tue 0700
GMT; Tue 0200 EST)
Consensus Forecast, ILO Unemployment Rate: 4.7%
Consensus Range, ILO Unemployment Rate: 4.6% to 4.9%
Consensus Forecast, Average Earnings - Y/Y: 3.6%
Consensus Range, Average Earnings - Y/Y: 3.5% to 3.7%
Earnings growth expected slightly lower at 3.6 percent rate
and unemployment seen flat at 4.7 percent in November.
Italy CPI for October (Tue 1000 CET; Tue 0900
GMT; Tue 0400 EST)
CPI Consensus Forecast, M/M: 0.9%
CPI Consensus Range, M/M: 0.9% to 0.9%
CPI Consensus Forecast, Y/Y: 5.4%
CPI Consensus Range, Y/Y: 5.4% to 5.4%
HICP Consensus Forecast, M/M: 1.2%
HICP Consensus Range, M/M: 1.2% to 1.2%
HICP Consensus Forecast, Y/Y: 5.6%
HICP Consensus Range, Y/Y: 5.6% to 5.6%
The consensus sees no revision in the final from the flash
with CPI up 0.9 percent on month and 5.4 percent on year for October.
Germany ZEW Survey for November (Tue 1100 CET; Tue 1000
GMT; Tue 0500 EST)
Consensus Forecast, Current Conditions: -34.7
Consensus Range, Current Conditions: -35.5 to -30.5
Consensus Forecast, Economic Sentiment: 28.2
Consensus Range, Economic Sentiment: 15.9 to 33.3
Forecasters expect the sentiment index almost unchanged at
28.2 in November from 28.1 in October.
Canada Housing Starts for October (Tue 0815 EST; Tue 1315
GMT)
Consensus Forecast, Annual Rate: 243K
Consensus Range, Annual Rate: 230K to 248K
Starts seen at 243K in October, down from 249K in September.
US Retail Sales for October (Tue 0830 EST; Tue 1330
GMT)
Consensus Forecast, Retail Sales - M/M: 0.2%
Consensus Range, Retail Sales - M/M: -0.3% to 0.6%
Consensus Forecast, Ex-Vehicles - M/M: 0.4%
Consensus Range, Ex-Vehicles - M/M: -0.1% to 0.5%
Consensus Forecast, Ex-Vehicles & Gas - M/M: 0.3%
Consensus Range, Ex-Vehicles & Gas - M/M: 0.3% to
0.4%
A modest 0.2 percent increase is the call for October after
a better 0.8 percent in September as rising prices force consumers to cut back.
US Imports and Export Prices for October (Tue 0830
EST; Tue 1330 GMT)
Consensus Forecast, Import Prices - M/M: 0.8%
Consensus Range, Import Prices - M/M: 0.2% to 1.7%
Import prices expected up 0.8 percent on the month in
October, with a boost from energy prices, after a 1.1 percent increase in
September, also lifted by energy.
US Industrial Production for October (Tue 0915 EST;
Tue 1415 GMT)
Consensus Forecast, Industrial Production - M/M: 0.1%
Consensus Range, Industrial Production - M/M: -0.3%
to 0.3%
Consensus Forecast, Manufacturing Output - M/M: 0.4%
Consensus Range, Manufacturing Output - M/M: 0.3% to 0.5%
Consensus Forecast, Capacity Utilization Rate: 76.8%
Consensus Range, Capacity Utilization Rate: 77.6% to
77.2%
Industrial output expected up a tiny 0.1 percent in October
with capacity utilization down to 76.8 percent from 76.9 percent in September.
US Business Inventories for September (Tue 1000 EST;
Tue 1500 GMT)
Consensus Forecast, M/M: 0.5%
Consensus Range, M/M: 0.4% to 0.6%
The consensus looks for inventories up 0.5 percent in
September after rising 0.4 percent in August.
US Housing Market Index for November (Tue 1000 EST;
Tue 1500 GMT)
Consensus Forecast, Index: 29
Consensus Range, Index: 28 to 30
Builder sentiment is subdued as potential buyers grapple
with high mortgage rates and builders face rising input costs. The index is
expected flat at 29 in November from 29 in October and down from 32 in
September.
Wednesday
Japan Merchandise Trade for October (Wed 0850 JST;
Tue 2350 GMT; Tue 1850 EST)
Consensus Forecast, Balance: -954.2 B
Consensus Range, Balance: -1,450.40 B to -643.20 B
Consensus Forecast, Imports - Y/Y: 27.0%
Consensus Range, Imports - Y/Y: 24.7% to 31.1%
Consensus Forecast, Exports - Y/Y: 22.0%
Consensus Range, Exports - Y/Y: 13.7% to 23.1%
Export values are expected to rise 22.0% on the year in
October, compared with a revised 16.5% increase in September, revised down from
the original 16.7%. This would mark 14 straight months of annual gains and
eight consecutive months of double-digit growth.
Despite facing headwinds from stiff U.S. tariffs that have
been in place since February 2025 and the outbreak of war between the U.S.,
Israel and Iran in February this year, Japanese exports have shown little sign
of weakening. Even exports to the U.S. have remained positive for seven
straight months through September, rising 22.9 percent in the latest month, led
by automobiles, drugs and semiconductor parts. Japan's trade balance with the
U.S. also posted a surplus of 391.7 billion yen in September.
Imports are seen rising for a ninth consecutive month, up
27.0 percent on the year in October after increasing 18.9% a month earlier. In
September, import gains were driven by crude oil, semiconductor-related
electronic components and liquefied natural gas.
This is expected to bring the country's trade balance to a
deficit for a sixth straight month in October, at 954.2 billion yen, compared
with a deficit of 556.48 billion yen in September.
Australia Wage Price Index for Third Quarter (Wed
1130 AET; Wed 0030 GMT; Tue 1930 EST)
Consensus Forecast, Q/Q: 0.9%
Consensus Range, Q/Q: 0.9% to 1.1%
Consensus Forecast, Y/Y: 3.4%
Consensus Range, Y/Y: 3.4% to 3.4%
Slightly faster wage growth expected at 0.9 percent on
quarter in Q3 after 0.8 percent in Q2 with a boost from public sector wages
even as private sector wages slowed.
UK CPI for October (Wed 0700 GMT; Wed 0200 EST)
Consensus Forecast, M/M: 0.5%
Consensus Range, M/M: 0.4% to 0.6%
Consensus Forecast, Y/Y: 3.6%
Consensus Range, Y/Y: 3.5% to 3.7%
Consensus Forecast, Core CPI - Y/Y: 2.8%
Consensus Range, Core CPI - Y/Y: 2.7% to 2.9%
As energy costs kick in, CPI expected to accelerate to show
gains of 0.5 percent on month and 3.6 percent on year in October from already
ugly 0.4 percent and 3.5 percent in September. Fortunately, annual core CPI
seen flat at 2.8 percent in October from September.
Eurozone HICP for October (Wed 1100 CET; Wed 1000
GMT; Wed 0500 EST)
Consensus Forecast, HICP M/M: 0.4%
Consensus Range, HICP M/M 0.4% to 0.4%
Consensus Forecast, HICP - Y/Y: 4.0%
Consensus Range, HICP - Y/Y: 4.0% to 4.0%
Consensus Forecast, Narrow Core - Y/Y: 2.5%
Consensus Range, Narrow Core - Y/Y: 2.5% to 2.5%
The consensus sees no revision in the final from the flash
with HICP at 0.4 percent on month and 4.0 percent on year, showing the impact
of rising energy costs. Narrow core expected unrevised at 2.5 percent on year.
US Housing Starts and Permits for October (Wed 0830
EST; Wed 1330 GMT)
Consensus Forecast, Starts - Annual Rate: 1.230 M
Consensus Range, Starts - Annual Rate: 1.190 M to 1.380
M
Consensus Forecast, Permits - Annual Rate: 1.378 M
Consensus Range, Permits - Annual Rate: 1.350 M to 1.380
M
Starts expected to remain depressed at a 1.230 million unit
rate in October versus 1.221 million in September and 1.288 million in August.
High mortgage rates continue to hurt housing demand and high input and labor
costs are hemming in builders.
US Pending Home Sales Index for October (Wed 1000
EST; Wed 1500 GMT)
Consensus Forecast, M/M: -1.2%
Consensus Range, M/M: -2.5% to 0%
The consensus looks for another negative reading, down 1.2
percent on the month, as homebuyers are sidelined by rising mortgage rates.
Thursday
Japan Machinery Orders for September (Thu 0850 JST; Wed
2350 GMT; Wed 1850 EST)
Consensus Forecast, M/M: -0.5%
Consensus Range, M/M: -4.0% to 1.8%
Consensus Forecast, Y/Y: 16.1%
Consensus Range, Y/Y: 6.6% to 18.7%
Monthly industry data compiled by the Japan Machine Tool
Builders Association showed a slowdown in machine tool orders in September,
which could indicate a slight decline in the countrys core machinery orders.
The core orders, which exclude ships and electric power, are expected to fall
0.5 percent on the month in September, following a 5.2 percent rise in August.
On a year-on-year basis, the orders are expected to post
another double-digit increase in September, climbing 16.1 percent, compared
with 18.6 percent a month earlier. After posting a 1.9 percent fall in May,
they rebounded to 16.9 percent growth and 11.2 percent in July.
Australia Labour Force Survey for October (Thu 1130
AET; Thu 0030 GMT; Wed 1930 EST)
Consensus Forecast, Employment - M/M: 27K
Consensus Range, Employment - M/M: 10K to 42K
Consensus Forecast, Unemployment Rate: 4.7%
Consensus Range, Unemployment Rate: 4.6% to 4.8%
Employment seen recovering a bit to a gain of 27,000 in
October after falling 39,000 in September. The jobless rate is expected steady
at 4.7 percent.
US Jobless Claims for Week of November 14 (Thu 0830 EST;
Thu 1330 GMT)
Consensus Forecast, Initial Claims - Level: 197 K
Consensus Range, Initial Claims - Level: 194 K to 200
K
Claims expected back down to 197K after rising 9K to 200K
last week.
US Philadelphia Fed Manufacturing Index for November (Thu
0830 EST; Thu 1330 GMT)
Consensus Forecast, Index: 23.2
Consensus Range, Index: 15.0 to 31.4
Business expansion expected to improve to an index of 23.2
in November from 20.9 in October.
US Leading Indicators for October (Thu 1000 EST; Thu
1500 GMT)
Consensus Forecast, M/M: 0.0%
Consensus Range, M/M: -0.1% to 0.2%
Leading index expected flat for a second straight month.
Friday
Japan CPI for October (Fri 0830 JST; Thu 2330 GMT;
Thu 1830 EST)
Consensus Forecast, CPI - Y/Y: 2.6%
Consensus Range, CPI - Y/Y: 2.3% to 2.8%
Consensus Forecast, Ex-Fresh Food - Y/Y: 2.4%
Consensus Range, Ex-Fresh Food - Y/Y: 2.3% to 2.6%
Consensus Forecast, Ex-Fresh Food & Energy - Y/Y:
2.3%
Consensus Range, Ex-Fresh Food & Energy - Y/Y: 2.3%
to 2.7%
Japans consumer inflation is expected to accelerate in two
of the three major readings in October as the uptrend in prices becomes clearer
and spreads across a wider range of goods and services, following a similar
trend seen in the countrys capital.
After all three key measures of the nationwide consumer
price index (CPI) rose above the Bank of Japans 2% inflation target in
September for the first time in six months, the October readings are expected
to show further gains, with two reaching their highest levels in 2026.
The core index, which excludes fresh food, is expected to
rise 2.4 percent, compared with 2.1 percent in September. This would be the
highest reading since December 2025, when it rose by the same amount.
The total CPI is projected to rise to 2.6 percent in October
from 2.1 percent in September, marking its highest level since November 2025,
when it increased 2.9 percent.
Meanwhile, the core-core figure, which excludes fresh food
and energy, is expected to decelerate to a 2.3 percent year-on-year rise in
October, compared with a 2.4 percent increase in the previous month.
China Loan Prime Rate for November (Fri 0915 CST; Fri
0115 GMT; Thu 2015 EST)
Consensus Forecast, 1-Year Rate - Change: 0 bp
Consensus Range, 1-Year Rate - Change: 0 bp to 0 bp
Consensus Forecast, 1-Year Rate - Level: 3.0%
Consensus Range, 1-Year Rate - Level: 3.0% to 3.0%
Consensus Forecast, 5-Year Rate - Change: 0 bp
Consensus Range, 5-Year Rate - Change: 0 bp to 0 bp
Consensus Forecast, 5-Year Rate - Level: 3.5%
Consensus Range, 5-Year Rate - Level: 3.5% to 3.5%
Rates expected unchanged again as the Chinese authorities
rely on fiscal measures to boost the flagging economy.
Germany PPI for October (Fri 0800 CET; Fri 0700 GMT; Fri
0200 EST)
Consensus Forecast, M/M: 0.6%
Consensus Range, M/M: 0.5% to 1.6%
Consensus Forecast, Y/Y: 7.3%
Consensus Range, Y/Y: 7.1% to 8.2%
The monthly increase in wholesale prices is expected lower
but still big at 0.6 percent, with an increase of 7.3 percent on year in
October. There were increases of 1.9 percent on month and 6.7 percent on year
in September.
France Business Climate Indicator for November (Fri 0845
CET; Fri 0745 GMT; Fri 0245 EST)
Consensus Forecast, Index: 96
Consensus Range, Index: 95 to 96
The indicator is seen at 96 in November, down from 97 in
October as business sentiment remains depressed.
Canada Retail Sales for September (Fri 0830 EST; Fri
1330 GMT)
Consensus Forecast, M/M: 0.7%
Consensus Range, M/M: 0.5% to 0.7%
Forecasters agree with Stats Canadas preliminary estimate
showing sales up 0.7 percent, a remarkably resilient showing despite rising
fuel costs and other worries.
Eurozone EC Consumer Confidence Flash for November (Fri
1600 CET; Fri 1500 GMT; Fri 1000 EST)
Consensus Forecast, Index: -17.8
Consensus Range, Index: -18.2 to -17.2
Consumer confidence seen basically flat at minus 17.8 in
November from -17.9 in October.
US Consumer Sentiment for November (Fri 1000 EST; Fri
1500 GMT)
Consensus Forecast, Index: 51.0
Consensus Range, Index: 50.8 to 53.3
Forecasters see no revision in the final from the flash at
51.0 for consumer sentiment. That was up from 48.0 in the October final and
flat from November 2025.
|