|
The Week Ahead: Highlights
Asia-Pacific Preview
New Zealand Rate Hike Expected; Australia Inflation Key
to RBA Decision
By Brian Jackson, Econoday Economist
Policy meetings will be the key focus in the Asia-Pacific
region in the week ahead. The Reserve Bank of New Zealand is widely
expected to raise policy rates by 25 basis points after rate hikes in early
July and early September. Officials advised at the last meeting that
further reduction in monetary stimulus was likely to be required to return
inflation to its target range of one percent to three percent. Data published
this week showed headline inflation fell from 4.1 percent in the three
months to June to 3.7 percent in the three months to September, but
officials noted that inflation would have been 3.2 percent were it not
for higher petrol prices. This may provide some assurance to the RBNZ that
broader price pressures are contained, but officials have indicated that
another rate hike will be closely considered at this meeting.
The Bank of Thailand will also hold its policy meeting in
the week ahead after leaving rates on hold again at its previous meeting
in late August. At that meeting, officials noted that growth in the
Thai economy had been low despite support from AI-related demand. They
also downgraded their assessment of the inflation outlook. Headline
inflation, however, has risen in the last two months from 1.95 percent in
July to 2.53 percent in August and 2.82 percent in September, close to the top
of the target range of one percent to three percent, while core inflation
has trended higher. Although officials have indicated that they are
content with current policy settings, they may note the recent increase in
inflation in their statement next week and update their guidance on the
policy outlook. Trade and industrial production data for Thailand will
also be published next week.
Australian inflation data will also be watched closely ahead
of the Reserve Bank of Australias next policy meeting in early November.
Monthly consumer inflation data and quarterly producer price
inflation data will be published. Officials raised policy rates for the
fourth time this year at their latest meeting in late September, citing
concerns that inflation remains elevated and that upside risks
were materialising. Just after that meeting, CPI data showed an increase
in inflation from 3.5 percent in July to 4.0 percent in August, further
above the target range of two percent to three percent. RBA officials will
be looking for evidence that price pressures are moderating in response to
previous policy tightening, but the data will likely reinforce their
concerns that inflation remains too high.
Elsewhere in the region, quarterly GDP and monthly retail
sales and industrial production data for South Korea will likely show the
impact of strong AI-related demand. Singapore and India will also
report industrial production data, while Hong Kong will report trade data.
US Preview
FOMC Up Next; Market Sees No Rate Move Until December
By Theresa Sheehan, Econoday Economist
The focus of the October 26 week will be the Federal Open
Market meeting on Tuesday and Wednesday, and Fed Chair Kevin Warshs press
briefing on Wednesday.
Most forecasters expect no change in the fed funds target
rate when the post-meeting statement is issued at 14:00 ET on Wednesday. There
are two main reasons.
First, a majority of the FOMC will want to wait a bit to see
if the softer labor market seen in the September employment report carries into
October. That data wont be available until Friday, November 6 at 8:30 ET.
Although other data like weekly jobless claims indicate that layoffs are not
prevalent, the balance between slow hiring and low firing may be tipping toward
no hiring. If so, the FOMC will have to pay more attention to the effect of
higher rates on the maximum employment side of the dual mandate even though
price stability as defined by the 2 percent inflation target remains out of
reach. The FOMC will take a cautious approach until the data is clearer when
the December 8-9 meeting rolls around. It remains to be seen if this leads to
a dissent in the vote with some members finding inflation in more urgent need
of a remedy.
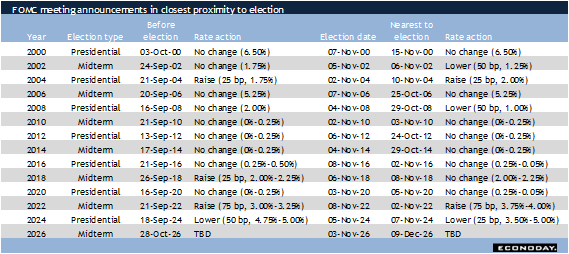
The FOMC may also want to wait until things are more settled
after the November 3 midterm election. Although Fed policymakers do their best
to set monetary policy apolitically, the upcoming meeting is less than a week
before the midterm election. Should the committee raise rates, it might be
interpreted as favoring the Democrats or at least trying to hurt Republican
chances of holding on to the House and/or Senate. FOMC participants will have
to weigh the demands of the US economy and their responsibility to lower
inflation against their credibility. Ironically, that credibility could be
called into question whether it is a failure to address inflation threats or
showing political favor.
Whichever, Fed Chair Kevin Warsh will have a challenging
press briefing when he takes the podium at 14:00 ET on Wednesday. Given his
determination to offer no forward guidance but only a broad economic framework
in relation to monetary policy, he will be saying as little as possible at this
juncture. Warsh is likely to get many questions direct and oblique about
the consequences of the upcoming election. He will answer none of them beyond
saying that monetary policy was and will be set according to the best available
information at the time of the meeting. He will strongly defend the
independence of policymakers.
It is also possible that Warsh will use the moment to
announce some decisions regarding his five-part reform program. At this
meeting, the FOMC will not be updating the summary of economic projections
(SEP). Depending on the outcome of some of the discussions regarding Fed
communications, Warsh could find this an appropriate moment to announce its
future or its discontinuance.
As a footnote, Fed policymakers will get the October senior
loan officers survey to consider regarding demand for and willingness to lend
to businesses and consumers. The report will be released to the public at 14:00
ET on Monday, November 2.
The Week Ahead: Econoday Consensus Forecasts
Monday
Singapore Industrial Production for September (Mon
1300 SGT; Thu 0500 GMT; Thu 0100 EDT)
Consensus Forecast, M/M: 0.5%
Consensus Range, M/M: 0.5% to 2.0%
Consensus Forecast, Y/Y: 7.2%
Consensus Range, Y/Y: 6.6% to 12.5%
The consensus looks for industrial output to rebound by 0.5
percent on the month in September after falling 0.5 percent in August.
Forecasters see output up 12.5 percent on year in September after rising 15.4
percent in August.
Germany Ifo Survey for October (Mon 1000 CET; Mon 0900
GMT; Mon 0500 EDT)
Consensus Forecast, Business Climate: 90.0
Consensus Range, Business Climate: 89.5 to 90.4
Consensus Forecast, Current Conditions: 89.9
Consensus Range, Current Conditions: 89.4 to 90.0
Consensus Forecast, Business Expectations: 90.2
Consensus Range, Business Expectations: 89.9 to 91.0
Forecasters see business sentiment holding near recent highs
with the business climate index expected at 90.0 in October after rising to
89.9 in September from 88.8 in August.
US Chicago Fed National Activity Index for September
(Mon 0830 EDT; Mon 1230 GMT)
Consensus Forecast, Index: -0.1
Consensus Range, Index: -0.1 to -0.1
An unimpressive -0.1 index is the call.
US Dallas Fed Manufacturing Survey for October (Mon
1030 EDT; Mon 1430 GMT)
Consensus Forecast, General Activity Index: 7.0
Consensus Range, General Activity Index: 7.0 to 9.0
Manufacturing is seen continuing its slow expansion with the
Dallas Fed index at 7 for October versus 9.8 in September.
Tuesday
South Korea GDP for Third Quarter (Tue 0800 KST; Mon
2300 GMT; Mon 1900 EDT)
Consensus Forecast, Q/Q: 0.7%
Consensus Range, Q/Q: 0.7% to 0.9%
Consensus Forecast, Y/Y: 3.2%
Consensus Range, Y/Y: 3.0% to 3.2%
Growth expected at 0.7 percent on quarter in Q3 and 3.2
percent on year.
Eurozone M3 Money Supply for September (Tue 1000
CEST; Tue 0800 GMT; Tue 0400 EDT)
Consensus Forecast, Y/Y - 3-Month Moving Average: 3.6%
Consensus Range, Y/Y - 3-Month Moving Average: 3.3%
to 3.6%
Money supply growth expected to speed up to 3.6 percent in
September from 3.4 percent in August.
US Durable Goods Orders for September (Tue
0830 EDT; Tue 1230 GMT)
Consensus Forecast, New Orders - M/M: 1.4%
Consensus Range, New Orders - M/M: -0.1% to 2.5%
Consensus Forecast, Ex-Transportation - M/M: 0.5%
Consensus Range, Ex-Transportation - M/M: 0.2% to 0.5%
Consensus Forecast, Core Capital Goods - M/M: 0.5%
Consensus Range, Core Capital Goods - M/M: 0.4% to 1.0%
Another robust rise in capex seen at 0.5 percent for core
capital goods as the AI-driven investment boom continues. Durables overall
expected up 1.4 percent, skewed up by aircraft, as usual.
US Case-Shiller Home Price Index for August (Tue 0900
EDT; Tue 1300 GMT)
Consensus Forecast, 20-City Adjusted - M/M: -0.1%
Consensus Range, 20-City Adjusted - M/M: -0.5% to
0.1%
Consensus Forecast, 20-City Unadjusted - Y/Y: 2.5%
Consensus Range, 20-City Unadjusted - Y/Y: 2.4% to
2.9%
The year-on-year rise in home prices is expected flat at 2.5
percent in August as housing price inflation remains muted amid weak demand.
US FHFA House Price Index for August (Tue 0900 EDT;
Tue 1300 GMT)
Consensus Forecast, M/M: 0.2%
Consensus Range, M/M: 0.1% to 0.3%
The consensus looks for a muted, trend-like 0.2 percent
increase in home prices on the month.
US Consumer Confidence for October (Tue 1000 EDT; Tue
1400 GMT)
Consensus Forecast, Index: 80.4
Consensus Range, Index: 78.8 to 83.5
The separate University of Michigan survey result showed
sentiment effectively flat at depressed levels in October from September as
consumers focus on high inflation and high gasoline prices in particular. The
consensus looks for a similar reading from the Conference Board report on
Tuesday with the consumer confidence index expected at 80.4 in October versus
81.9 in September and 88.6 in August.
US New Home Sales for September (Tue 1000 EDT; Tue
1400 GMT)
Consensus Forecast, Annual Rate: 651K
Consensus Range, Annual Rate: 638K to 660K
Surprisingly bad homebuilder sentiment and weak housing
starts reports have reflected high mortgage rates and consumers inflation
worries, bad news for the housing market. The consensus looks for new home
sales down to a 651K rate in September from 684K in August.
Wednesday
Australia Monthly CPI for September (Wed 1130 AEDT;
Wed 0030 GMT; Tue 2030 EDT)
Consensus Forecast, CPI - Y/Y: 4.2%
Consensus Range, CPI - Y/Y: 4.1% to 4.2%
CPI expected higher at 4.2 percent on year in September versus
4.0 percent in August.
New Zealand RBNZ Announcement (Wed 1400 NZDT; Wed
0100 GMT; Tue 2100 EDT)
Consensus Forecast, Change: 25 bp
Consensus Range, Change: 0 bp to 25 bp
Consensus Forecast, Level: 3.00%
Consensus Range, Level: 2.75% to 3.00%
The bank will move by 25 bp now and signal more to come as
it reacts to rising energy prices and the threat of higher inflation headed
into year end.
Germany GfK Consumer Climate for October (Wed 0700
CET; Tue 0600 GMT; Tue 0200 EDT)
Consensus Forecast, Index: -29.6
Consensus Range, Index: -32.0 to -29.0
The consensus sees the index a bit better at minus 29.6 for
November versus minus 30.6 in October.
India Industrial Production for September (Wed 1600
IST; Wed 1030 GMT; Wed 0630 EDT)
Consensus Forecast, Y/Y: 7.2%
Consensus Range, Y/Y: 7.2% to 7.4%
Forecasters expect industrial production up 7.2 percent on
year in September, down from 8.0 percent in August.
US International Trade in Goods (Advance) for September (Wed
0830 EDT; Wed 1230 GMT)
Consensus Forecast, Balance: -$129.0 B
Consensus Range, Balance: -$136.8 B to -$88 B
The consensus sees another huge goods trade gap at $129.0
billion versus $136.6 billion in August.
US Wholesale Inventories (Advance) for September (Wed
0830 EDT; Wed 1230 GMT)
Consensus Forecast, M/M: 0.3%
Consensus Range, M/M: 0.2% to 0.7%
A 0.3 percent increase is expected in September after a 0.7
percent rise in August.
Canada Bank of Canada Announcement (Wed 0945 EDT; Wed
1345 GMT)
Consensus Forecast, Change: 0 bp
Consensus Range, Change: 0 bp to 25 bp
Consensus Forecast, Level: 2.25%
Consensus Range, Level: 2.25% to 2.50%
BOC policy-makers have been sounding the alarm about the
threat of inflation, which suggests a rate increase is coming but most
forecasters think Canadas economy is weak enough that the bank can wait a bit
longer to move. That suggests no action this week but a rate hike is coming as
soon as December.
US FOMC Announcement (Wed 1400 EDT; Wed 1800 GMT)
Consensus Forecast, Change: 0 bp
Consensus Range, Change: 0 bp to 25 bp
Consensus Forecast, Federal Funds Rate - Target Range: 3.75%-4.00%
Consensus Range, Federal Funds Rate - Target Range:
3.75%-4.00% to 4.00%-4.25%
The consensus looks for no action. Weak September jobs data
and the proximity of the midterm elections argue for the Fed to wait until
December to move.
Thursday
Eurozone EC Economic Sentiment for October (Thu 1100
CET; Thu 1000 GMT; Thu 0600 EDT)
Consensus Forecast, Economic Sentiment: 97.6
Consensus Range, Economic Sentiment: 97.1 to 98.1
Consensus Forecast, Industry Sentiment: -3.8
Consensus Range, Industry Sentiment: -4.5 to -3.3
Consensus Forecast, Consumer Sentiment: -17.9
Consensus Range, Consumer Sentiment: -17.9 to -17.9
Economic sentiment expected to erode to 97.6 in October from
97.9 in September.
US GDP for Third Quarter (Thu 0830 EDT; Thu 1230 GMT)
Consensus Forecast, Quarter over Quarter - Annual Rate:
3.1%
Consensus Range, Quarter over Quarter - Annual Rate: 2.5%
to 4.1
Consensus Forecast, Personal Consumption Expenditures -
Annual Rate: 3.5%
Consensus Range, Personal Consumption Expenditures -
Annual Rate: 3.2% to 3.9%
The consensus sees GDP growth at 3.1 percent in Q3, up from
2.2 percent in Q2. The strong showing reflects extraordinary capex due to the
AI buildout while the rest of the economy remains weak.
US Jobless Claims for Week of October 24 (Thu 0830
EDT; Thu 1230 GMT)
Consensus Forecast, Initial Claims - Level: 198K
Consensus Range, Initial Claims - Level: 190K to 200K
Another steady claims reading expected at 198K, remaining
below 200K, suggesting remarkable resilience in the job market.
US Personal Income and Outlays for September (Thu
0830 EDT; Thu 1230 GMT)
Consensus Forecast, Personal Income - M/M: 0.3%
Consensus Range, Personal Income - M/M: 0.2% to 0.4%
Consensus Forecast, Personal Consumption Expenditures -
M/M: 0.5%
Consensus Range, Personal Consumption Expenditures - M/M:
0.3% to 0.8%
Consensus Forecast, PCE Price Index - M/M: 0.5%
Consensus Range, PCE Price Index - M/M: 0.4% to 0.6%
Consensus Forecast, PCE Price Index - Y/Y: 3.6%
Consensus Range, PCE Price Index - Y/Y: 3.3% to 4.0%
Consensus Forecast, Core PCE Price Index - M/M: 0.3%
Consensus Range, Core PCE Price Index - M/M: 0.2% to
0.4%
Consensus Forecast, Core PCE Price Index - Y/Y: 3.1%
Consensus Range, Core PCE Price Index - Y/Y: 3.0% to
3.1%
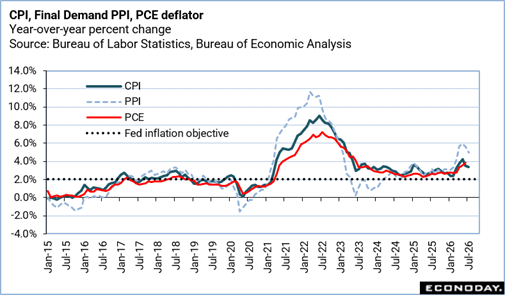
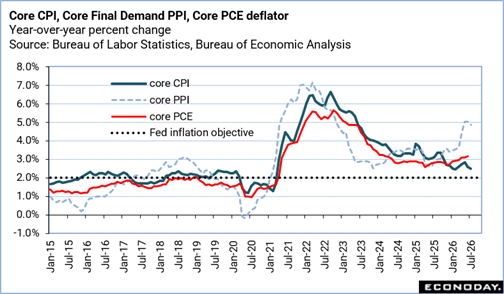
PCE prices to remain elevated with total up an ugly 3.6
percent and core up 3.0 percent on year in September. Thats not the 2.0
percent Fed Chair Kevin Warsh promised. Meanwhile, spending continues strong
even as consumers say they are not inclined to spend money. The consensus sees
nominal sales up 0.5 percent on the month!
Eurozone ECB Announcement (Thu 1415 CET; Thu 1315
GMT; Thu 0915 EDT)
Consensus Forecast, Refi Rate Change: 0 bp
Consensus Range, Refi Rate Change: 0 bp to 0 bp
Consensus Forecast, Refi Rate Level: 2.65%
Consensus Range, Refi Rate Level: 2.65% to 2.65%
Consensus Forecast, Deposit Rate Change: 0 bp
Consensus Range, Deposit Rate Change: 0 bp to 0 bp
Consensus Forecast, Deposit Rate Level: 2.50%
Consensus Range, Deposit Rate Level: 2.50% to 2.50%
The consensus sees the ECB on hold this time after their 25
bp rate move in September -- with one more rate hike expected in December.
Thats assuming we dont see serious financial instability with French yield
spreads continuing to blow out.
Friday
South Korea Industrial Production for September (Fri
0800 KST; Thu 2300 GMT; Thu 1900 EDT)
Consensus Forecast, M/M: 2.0%
Consensus Range, M/M: 0.4% to 2.0%
Industrial output expected to rebound by 2.0 percent on the
month in September after dropping by 4.8 percent in August.
Japan Tokyo CPI for October (Fri 0830 JST; Thu 2330
GMT; Thu 1930 EDT)
Consensus Forecast, CPI - Y/Y: 2.7%
Consensus Range, CPI - Y/Y: 2.6% to 2.9%
Consensus Forecast, Ex-Fresh Food - Y/Y: 2.7%
Consensus Range, Ex-Fresh Food - Y/Y: 2.6% to 2.8%
Consensus Forecast, Ex-Fresh Food & Energy - Y/Y:
2.8%
Consensus Range, Ex-Fresh Food & Energy - Y/Y: 2.5%
to 3.0%
Japan Unemployment Rate for September (Fri 0830 JST;
Thu 2330 GMT; Thu 1930 EDT)
Consensus Forecast, Rate: 2.5%
Consensus Range, Rate: 2.4% to 2.5%
Japan Industrial Production for September (Fri 0850
JST; Thu 2350 GMT; Thu 1950 EDT)
Consensus Forecast, M/M: 1.1%
Consensus Range, M/M: 0.1% to 1.3%
Consensus Forecast, Y/Y: 0.8%
Consensus Range, Y/Y: -0.2% to 1.0%
Japan Retail Sales for September (Fri 0850 JST; Thu
2350 GMT; Thu 1950 EDT)
Consensus Forecast, M/M: 0.6%
Consensus Range, M/M: 0.1% to 1.0%
Consensus Forecast, Y/Y: 3.3%
Consensus Range, Y/Y: 3.0% to 4.7%
Japan Bank of Japan Announcement (Fri 1130 JST; Fri
0230 GMT; Thu 2230 EDT)
Consensus Forecast, Change: 0 bp
Consensus Range, Change: 0 bp to 0 bp
Consensus Forecast, Level: 1.25%
Consensus Range, Level: 1.25% to 1.25%
At its Oct. 29-30 meeting, the Bank of Japans nine-member
board is expected to decide to leave the target for the overnight interest rate
unchanged at 1.25% in a unanimous or majority vote after raising it to the
level from 1% in a 7 to 2 vote in September to keep underlying inflation from
deviating upward from the banks 2% price stability target.
Judging from recent remarks by Governor Kazuo Ueda, the bank is on course
toward lifting the short-term interest rate further to a more neutral level to
reduce the degree of monetary stimulus but upside risks to inflation is not
urgent enough to require a back-to-back rate hike.
France GDP Flash for Third Quarter (Fri 0630 CET; Fri
0530 GMT; Fri 0130 EDT)
Consensus Forecast, Q/Q: 0.1%
Consensus Range, Q/Q: 0.0% to 0.2%
Consensus Forecast, Y/Y: 0.3%
Consensus Range, Y/Y: 0.1% to 0.4%
Growth expected almost nonexistent in Q1 with an increase of
0.1 percent on quarter and 0.3 percent on year.
France CPI for October (Fri 0745 CET; Fri 0645 GMT;
Fri 0245 EDT)
Consensus Forecast, M/M: 0.3%
Consensus Range, M/M: 0.2% to 0.3%
Consensus Forecast, Y/Y: 3.2%
Consensus Range, Y/Y: 3.2% to 3.6%
Consensus Forecast, HICP - M/M: 0.3%
Consensus Range, HICP - M/M: 0.1% to 0.3%
Consensus Forecast, HICP - Y/Y: 3.6%
Consensus Range, HICP - Y/Y: 3.4% to 3.6%
CPI expected up 0.3 percent on month and 3.2 percent on year
in the preliminary October report.
Switzerland KOF Swiss Leading Indicator for October (Fri
0800 CEST; Fri 0700 GMT; Fri 0300 EDT)
Consensus Forecast, Index: 107.0
Consensus Range, Index: 106.9 to 108.0
Confidence expected to take a hit in October at 107.0 versus
109.1 in September.
Italy GDP for Third Quarter (Fri 0900 CET; Fri 0800
GMT; Fri 0400 EDT)
Consensus Forecast, Q/Q: 0.1%
Consensus Range, Q/Q: 0.1% to 0.2%
Consensus Forecast, Y/Y: 1.0%
Consensus Range, Y/Y: 0.9% to 1.2%
Italian GDP expected up 0.1 percent in Q3 from Q2 and 1.0
percent from a year ago, pretty similar to 0.2 percent and 1.0 percent in Q2.
Germany Unemployment Rate for October (Fri 0955 CET; Fri
0855 GMT; Fri 0455 EDT)
Consensus Forecast, Rate: 6.4%
Consensus Range, Rate: 6.4% to 6.4%
Jobless rate never seems to stray from 6.4 percent.
Germany GDP Flash for Third Quarter (Fri 1000 CEST; Fri
0900 GMT; Fri 0500 EDT)
Consensus Forecast, Q/Q: 0.1%
Consensus Range, Q/Q: -0.1% to 0.2%
Consensus Forecast, Y/Y: 1.1%
Consensus Range, Y/Y: 0.9% to 1.2%
GDP expected up 0.1 percent in Q3 from Q2 and 1.1 percent
from a year ago.
Italy CPI for October (Fri 1000 CEST; Fri 0900 GMT;
Fri 0500 EDT)
Consensus Forecast, M/M: 0.3%
Consensus Range, M/M: 0.0% to 0.4%
Consensus Forecast, Y/Y: 4.5%
Consensus Range, Y/Y: 4.5% to 4.7%
CPI expected up 0.3 percent on the month and 4.5 percent
from a year ago in October.
Eurozone GDP Flash for Third Quarter (Fri 1100 CET; Fri
1000 GMT; Fri 0600 EDT)
Consensus Forecast, Q/Q: 0.2%
Consensus Range, Q/Q: -0.1% to 0.3%
Consensus Forecast, Y/Y: 1.0%
Consensus Range, Y/Y: 0.8% to 1.1%
GDP expected up 0.2 percent in Q3 from Q2 and up 1.0 percent
from a year ago.
Eurozone Unemployment Rate for September (Fri 1100
CET; Fri 1000 GMT; Fri 0600 EDT)
Consensus Forecast, Rate: 6.4%
Consensus Range, Rate: 6.4% to 6.4%
The jobless rate is expected steady at 6.4 percent in
September.
Canada Monthly GDP for August (Fri 0830 EDT; Fri 1230
GMT)
Consensus Forecast, M/M: 0.2%
Consensus Range, M/M: 0.0% to 0.2%
Forecasters agree with Statistics Canadas preliminary
estimate calling for growth of 0.2 percent in August from July.
US Employment Cost Index for Third Quarter (Fri 0830
EDT; Fri 1230 GMT)
Consensus Forecast, Q/Q: 0.8%
Consensus Range, Q/Q: 0.6% to 0.9%
ECI seen up 0.8 percent in Q3 from Q2.
Germany CPI for October (Fri 1400 CET; Fri 1300 GMT; Fri
0900 EDT)
Consensus Forecast, M/M: 0.1%
Consensus Range, M/M: 0.0% to 0.3%
Consensus Forecast, Y/Y: 3.1%
Consensus Range, Y/Y: 2.9% to 3.4%
Consensus Forecast, HICP - M/M: 0.2%
Consensus Range, HICP - M/M: 0.1% to 0.3%
Consensus Forecast, HICP - Y/Y: 3.1%
Consensus Range, HICP - Y/Y: 3.1% to 3.3%
CPI increases expected at 0.1 percent m/m and 3.1 percent y/y
in October versus 0.6 percent and 3.3 percent in September.
US Chicago PMI for October (Fri 0945 EDT; Fri 1345
GMT)
Consensus Forecast, Index: 56.0
Consensus Range, Index: 50.0 to 57.2
Index expected lower but still strong at 56.0 in October
versus 56.8 in September.
China CFLP Composite PMI for October (Fri 0930 CST; Fri
0130 GMT; Thu 2130 EDT)
Consensus Forecast, Manufacturing Index: 50.1
Consensus Range, Manufacturing Index: 49.9 to 50.3
Manufacturing index expected at 50.1 in October, flat from
September, suggesting no change in business activity on the month.
|