|
The Week Ahead: Highlights
Asia-Pacific Preview
Reserve Bank of India Rate Move Next
By Brian Jackson, Econoday Economist
A key event in the week ahead will be the Reserve Bank of
India policy decision. The RBIs last policy meeting was in early August, with
officials leaving policy rates on hold. Although they expressed concerns about
the impact of the Iran conflict on growth and inflation, they judged then that
there was little evidence that higher food and fuel prices would boost broader
price pressures.
Since then, however, headline CPI inflation has increased
from 4.48 percent in April to 4.44 percent in July and 4.82 percent in August,
its highest level since late 2024 and further above the mid-point of the RBI's
target range of two percent to six percent. Officials indicated in August that
they are ready to tighten policy if necessary to align inflation with their
target, and the latest CPI data may be enough to prompt a rate hike.
This months cycle of PMI surveys will be completed next
week, with September reports due for Singapore, Hong Kong and Indias services
sector. PMI surveys published this week mostly showed improved conditions
across the region, with ongoing strength in AI demand supporting production,
new orders and sentiment. August PMI surveys showed contraction in the Hong
Kong economy but the strongest growth since 2022 in Singapore. Taiwan will also
report trade data in the week ahead, while the monthly survey of Australian
consumer sentiment will be published.
Thai inflation data for September in the week ahead may
shift the assessment of the inflation outlook for officials at the Bank of
Thailand. Policy rates were left on hold at their last meeting in late August,
with officials advising then that they expected both headline and core
inflation would be lower than they previously anticipated. Headline inflation
rose in August for the first time in five months while core inflation rose for
the sixth consecutive month to its highest level since 2023.
US Preview
Fed Speakers, FOMC Minutes in Focus on Light Data Week
By Theresa Sheehan, Econoday Economist
It is a light economic data calendar in the October 5 week
situated between the September employment data on October 2 and the next big
inflation report of the consumer price index for September at 8:30 ET on
Wednesday, October 14.
The release of the minutes of the Setpemer15-16 FOMC meeting
will be carefully parsed for any hints of where various participants stand on
future monetary policy, especially if another rate hike is in the near future.
A number of Fed policymakers have spoken in recent days, so surprises should be
few. The minutes may also have a review of discussions regarding Fed
communications policy especially in regard to the summary of economic
projections (SEP) and any adjustments to balance sheet policy to reduce its
size more quickly. Chair Kevin Warsh has been explicit that he believes the
balance sheet is larger than necessary to provide ample reserves and a cushion
against financial shocks.
Perhaps the most interesting data in the week will be the
preliminary University of Michigan consumer sentiment index and inflation
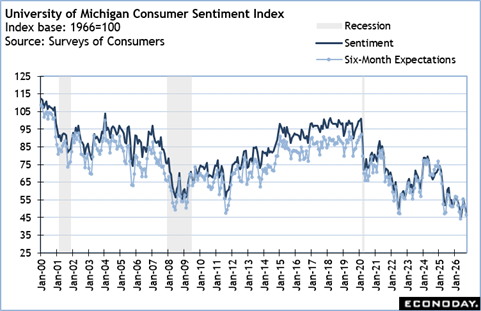
expectations for October. The September final reading for the sentiment index
was 48.1 which was the second lowest on record after 44.8 in May 2026. October
isnt likely to feel much better to consumers with the amping up of harsh
campaign rhetoric, worries about inflation and interest rates, and violence in
the Middle East showing no signs of easing. The index readings remain consistent
with signaling a recession even though other economic data points to expansion.
While survey data may not fully reflect actual economic
conditions, gloomy consumers are less apt to spend. However, some of that
reluctance may be overcome by anticipation of higher prices for and/or
shortages of goods. Consumers are stocking up on imported items that are
pricing higher due to tariffs and escalating transportation costs. The survey
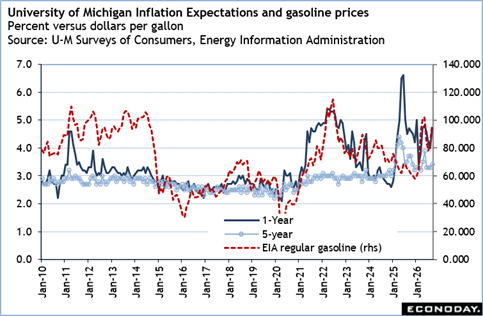
of consumers puts the anticipated 1-year inflation expectations measure at up
4.7 percent in September after 4.0 percent in August and the 5-year measure at
up 3.4 percent from 3.3 percent in the prior month. Given current elevated
energy costs for household expenses for gasoline, heating oil, and propane,
these measures probably will inch higher.
The Week Ahead: Econoday Consensus Forecasts
Monday
France PMI Composite Final for September (Mon 0850
CEST; Mon 0650 GMT; Mon 0250 EDT)
Consensus Forecast, Composite Index: 51.2
Consensus Range, Composite Index: 51.2 to 51.2
Consensus Forecast, Services Index: 51.4
Consensus Range, Services Index: 51.4 to 51.4
Forecasters see no revision in the final from the flash with
the composite unchanged at 51.2. That is up significantly from 48.5 in the
August final.
Germany PMI Composite Final for September (Mon
0955 CEST; Mon 0755 GMT; Mon 0355 EDT)
Consensus Forecast, Composite Index: 53.8
Consensus Range, Composite Index: 53.8 to 53.8
Consensus Forecast, Services Index: 52.9
Consensus Range, Services Index: 52.9 to 52.9
Forecasters see no revision in the final from the flash with
the composite unchanged at 53.8. That is down from 51.8 in the August final.
Eurozone PMI Composite Final for September (Mon
1000 CEST; Mon 0800 GMT; Mon 0400 EDT)
Consensus Forecast, Composite Index: 53.1
Consensus Range, Composite Index: 53.1 to 53.1
Consensus Forecast, Services Index: 53.0
Consensus Range, Services Index: 53.0 to 53.0
Forecasters see no revision in the final from the flash with
the composite unchanged at 53.1. That is up from 52.0 in the August final.
UK PMI Composite Final for September (Mon 0930
BST; Mon 1030 GMT; Mon 0430 EDT)
Consensus Forecast, Composite Index: 51.7
Consensus Range, Composite Index: 51.7 to 51.7
Consensus Forecast, Services Index: 51.7
Consensus Range, Services Index: 51.7 to 51.7
Forecasters see no revision in the final from the flash with
the composite unchanged at 51.7. That is down from 52.5 in the August final.
Eurozone PPI for August (Mon 1100 CEST; Mon 0900 GMT;
Mon 0500 EDT)
Consensus Forecast, Y/Y: 6.6%
Consensus Range, Y/Y: 6.5% to 7.1%
Wholesale prices are expected to rise 6.6 percent on year in
August, up from 5.8 percent in July.
US PMI Composite Final for September (Mon 0945 EDT; Mon
1345 GMT)
Consensus Forecast, Composite Index: 58.4
Consensus Range, Composite Index: 57.3 to 58.4
Consensus Forecast, Services Index: 58.7
Consensus Range, Services Index: 57.7 to 58.7
Forecasters see no revision in the final from the flash with
the composite unchanged at a very strong 58.4. That is up from 56.0 in the
August final.
US ISM Services Index for September (Mon 1000 EDT; Mon
1400 GMT)
Consensus Forecast, Index: 55.0
Consensus Range, Index: 54.5 to 56.0
ISM services expected pretty flat at 55.0 for September
after 55.4 in August as growth seen continuing at the same pace, just as the
ISM manufacturing report showed stable growth there.
Tuesday
Germany Manufacturing Orders for August (Tue 0800
CEST; Tue 0600 GMT; Tue 0200 EDT)
Consensus Forecast, M/M: -1.0%
Consensus Range, M/M: -1.5% to -0.6%
Consensus Forecast, Y/Y: 13.1%
Consensus Range, Y/Y: 12.2% to 13.6%
Orders expected to fall back by 1.0 percent on the month in
August after surging by 2.5 percent in July from June.
Eurozone Retail Sales for August (Tue 1100 CEST; Tue 0900
GMT; Tue 0500 EDT)
Consensus Forecast, M/M: 0.3%
Consensus Range, M/M: -0.4% to 0.4%
Consensus Forecast, Y/Y: 1.1%
Consensus Range, Y/Y: 0.1% to 1.2%
Sales expected up a moderate 0.3 percent on the month in
August after falling 0.6 percent in July.
Canada Merchandise Trade for August (Tue 0830 EDT; Tue
1230 GMT)
Consensus Forecast, Balance: C$1.5 B
Consensus Range, Balance: C$1.3 B to C$1.8 B
Canadas trade surplus seen wider at C$1.5 billion in August
from C$0.769 billion in July.
US International Trade in Goods and Services for August (Tue
0830 EDT; Tue 1230 GMT)
Consensus Forecast, Balance: -$ 99.0 B
Consensus Range, Balance: -$103.0 B to -$83.8 B
The trade gap is expected to widen to $99.0 billion in
August from $88.6 billion in July.
Wednesday
India Reserve Bank of India Announcement (ANYTIME)
Consensus Forecast, Change: 25 bp
Consensus Range, Change: 0 bp to 25 bp
Consensus Forecast, Level: 5.50%
Consensus Range, Level: 5.25% to 5.50%
The RBI has signaled it is ready to raise rates if inflation
misbehaves, which it has.
Sweden CPI Flash for September (Wed 0800 CEST; Wed
0600 GMT; Wed 0200 EDT)
Consensus Forecast, M/M: 1.0%
Consensus Range, M/M: 1.0% to 1.0%
Consensus Forecast, Y/Y: 1.2%
Consensus Range, Y/Y: 1.2% to 1.2%
Energy costs expected to lift CPI 1.0 percent on the month.
Germany Industrial Production for August (Wed 0800
CEST; Wed 0600 GMT; Wed 0200 EDT)
Consensus Forecast, M/M: 0.5%
Consensus Range, M/M: -0.7% to 1.5%
Consensus Forecast, Y/Y: 0.7%
Consensus Range, Y/Y: -2.0% to 1.9%
Output seen rebounding by 0.5 percent on the month in August
after falling 1.1 percent in July.
US Consumer Credit for August (Wed 1500 EDT; Wed 1900
GMT)
Consensus Forecast, M/M: $ 15.0 B
Consensus Range, M/M: $4.0 B to $15.6 B
The consensus sees a $15 billion increase in consumer credit
outstanding on the month.
Thursday
Germany Merchandise Trade for August (Thu 0800 CEST; Thu
0600 GMT; Thu 0200 EDT)
Consensus Forecast, Balance: E18.0 B
Consensus Range, Balance: E 18.0 B to E18.5 B
The trade surplus is expected to narrow to E18.0 billion in
August from E21.3 billion in July.
US Jobless Claims for Week of October 03 (Thu 0830
EDT; Thu 1230 GMT)
Consensus Forecast, Initial Claims - Level: 200 K
Consensus Range, Initial Claims - Level: 199K to 205K
Claims expected up a bit at 200K in the latest week after
declining to 197K last week.
Friday
Japan Household Spending for August (Fri 0830 JST; Fri
2330 GMT; Fri 1930 EDT)
Consensus Forecast, M/M: -0.4%
Consensus Range, M/M: -0.4% to 1.4%
Consensus Forecast, Y/Y: -4.2%
Consensus Range, Y/Y: -4.4% to -2.4%
Japanese households are becoming increasingly cautious about
spending as upward pressure on prices shows few signs of easing. Real spending
by households of two or more persons is expected to drop for the ninth straight
month on the year in August, while cooler temperatures may have limited
purchases of summer-related items. Several indicators pointed to a slowdown in
consumer spending in August. New passenger car registrations slowed, while
nationwide supermarket sales rose only slightly. Meanwhile, sales growth at
nationwide department stores and convenience stores also slowed, underscoring
that rising prices may be making households more cautious about spending.
In addition, natural disasters, including a powerful
magnitude 7.1 earthquake that struck Kumamoto on Japans southern main island
of Kyushu in late July and heavy rain and flooding in Chiba in mid-August, as
well as lower temperatures in central and northern regions, including Tokyo,
could have affected sales of summer-related items. August real household
spending by two or more persons is forecast to drop 4.2 percent on the year
after falling 3.6 percent a month earlier. On the month, spending is expected
to fall 0.3 percent for the first time in two months after rising 0.5 percent
in July.
Italy Industrial Production for August (Fri 1000
CEST; Fri 0800 GMT; Fri 0400 EDT)
Consensus Forecast, M/M: 0.0%
Consensus Range, M/M: -0.2% to 0.2%
Output expected flat on the month for August.
Brazil CPI for September (Fri 0900 BRT; Fri 1200 GMT;
Fri 0800 EDT)
Consensus Forecast, Y/Y: 4.44%
Consensus Range, Y/Y: 4.30% to 4.47%
CPI inflation expected at 4.44 percent on year in September.
Canada Labour Force Survey for September (Fri 0830
EDT; Fri 1230 GMT)
Consensus Forecast, Employment - M/M: 10K
Consensus Range, Employment - M/M: 5K to 65K
Consensus Forecast, Unemployment Rate: 6.5%
Consensus Range, Unemployment Rate: 6.4% to 6.5%
The consensus looks for anemic job growth at 10K leading to
an uptick in the jobless rate to 6.5 percent from 6.4 percent in August.
US Consumer Sentiment for October (Fri 1000 EDT; Fri
1400 GMT)
Consensus Forecast, Index: 48.0
Consensus Range, Index: 47.0 to 49.0
The index is expected to ebb to a super-low 47.0 from an
already gloomy 47.6 in September.
|